Imagine being 45 years old. You wake up naturally, sip coffee on your porch, and spend your day exactly how you want — reading, hiking, traveling, or working on passion projects. You’re not stressed about money because your investments cover your living expenses.
That’s not a fantasy. That’s the promise of the FIRE movement.
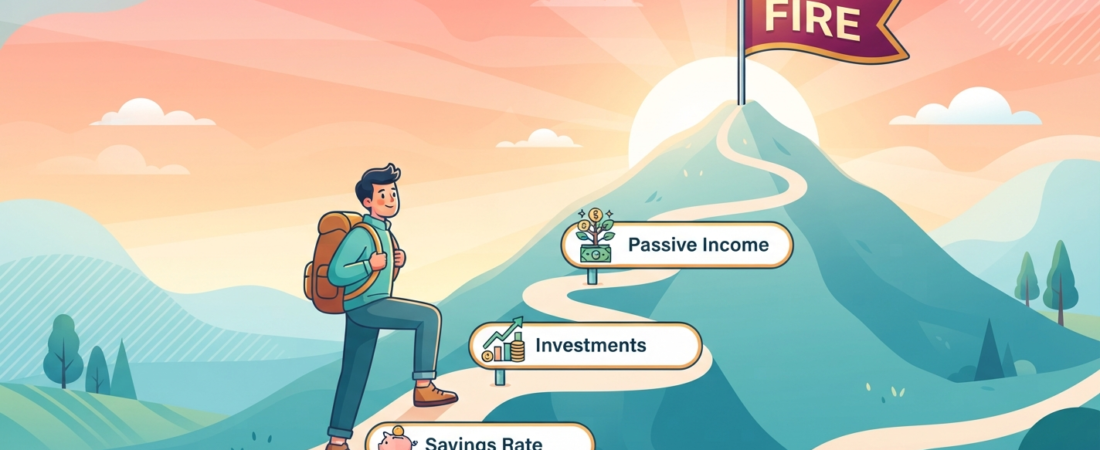
FIRE stands for Financial Independence, Retire Early. It’s a lifestyle and investing strategy that has exploded in popularity over the past decade. And while it sounds extreme, the core principles are actually simple:
- Spend less than you earn
- Invest the difference aggressively
- Build a portfolio large enough to fund your life forever
- Retire decades earlier than the traditional age of 65
If that sounds appealing, you’re in the right place. In this guide, I’ll explain exactly how FIRE works, the math behind it, the different variations, and the steps you need to take to make it a reality.
https://wealthytraders.online/retirement-planning-in-your-30s/
This article builds on everything you’ve learned in this series — from Retirement Planning in Your 30s → to 401(k) vs IRA → — because FIRE is simply retirement planning taken to the next level.
Let’s dive in.
What Is the FIRE Movement?
FIRE is a lifestyle movement focused on achieving financial independence as early as possible, then choosing to “retire” from traditional 9-to-5 work. It started gaining mainstream attention in the 2010s, thanks to blogs and communities like Mr. Money Mustache and the FIRE subreddit.
The key distinction between FIRE and normal retirement:
- Traditional retirement → Work until you’re 65, then live off savings and Social Security.
- FIRE retirement → Save aggressively (often 50–70% of income), invest heavily, and reach financial independence in 10–20 years, then leave traditional work.
Important: FIRE doesn’t necessarily mean you’ll never work again. Many FIRE enthusiasts continue to work — but on their own terms, doing things they enjoy, or in part-time roles. The key is having the freedom to choose.
The Math Behind FIRE: The 4% Rule and 25x Rule
The foundation of FIRE math rests on two simple concepts:
The 4% Rule
The 4% rule states that once you’re retired, you can safely withdraw 4% of your investment portfolio each year without running out of money over a 30-year retirement. It’s based on historical stock market returns and inflation data.
So, if your portfolio is $1 million, you can withdraw $40,000 in the first year of retirement, and adjust for inflation each year after that.
The 25x Rule
To calculate how much you need to retire, simply multiply your annual expenses by 25.
In other words: if you spend $40,000 per year, you need $1,000,000 invested.
If you spend $60,000 per year, you need $1,500,000.
This is the target number. It’s simple, powerful, and universal.
The Most Important Number: Your Savings Rate
If there’s one metric that determines how fast you achieve FIRE, it’s your savings rate — the percentage of your income you save and invest.
Your savings rate directly determines your time to financial independence:
| Savings Rate | Years to FIRE (Estimate) |
|---|---|
| 10% | 51 years |
| 20% | 37 years |
| 30% | 28 years |
| 40% | 22 years |
| 50% | 17 years |
| 60% | 12.5 years |
| 70% | 8.5 years |
| 80% | 5.5 years |
Let that sink in. If you save 10% of your income, it’ll take about 51 years. If you save 50%, it takes just 17 years. If you can save 70%, you’re looking at less than a decade.
This is why FIRE followers are obsessed with both increasing income AND reducing expenses. It’s not about making $500,000 a year; it’s about keeping as much of what you make as possible.
The Different Types of FIRE (Find Your Flavor)
Not all FIRE is the same. There are several variations, depending on your lifestyle goals and spending needs:
Lean FIRE
- Goal: Minimalism and extreme frugality.
- Portfolio: Enough to cover very low annual expenses (often under $40,000).
- Lifestyle: Tight budgeting, simple living, geographical arbitrage (living in low-cost countries).
- Best for: People who truly value time over money and enjoy simple pleasures.
Fat FIRE
- Goal: Maintain your current (or more luxurious) lifestyle in early retirement.
- Portfolio: Larger, often $2 million or more, to support expenses above $80,000/year.
- Lifestyle: No need to count every penny. Travel, fine dining, expensive hobbies.
- Best for: High earners who want to stop working but keep their lifestyle.
Barista FIRE
- Goal: A hybrid approach. Achieve enough investments to cover partial expenses, but continue working a part-time or enjoyable low-stress job for the rest.
- Portfolio: Covers 50–80% of living expenses.
- Lifestyle: You have the freedom to work as a barista (or any fun job) for healthcare benefits and extra cash.
- Best for: People who don’t want to fully stop working, but want to escape corporate pressure.
Coast FIRE
- Goal: Save enough in your early years that, thanks to compound interest, you’ll reach your target retirement number by traditional retirement age — without adding another dollar.
- Portfolio: Enough to grow to your target by age 65.
- Lifestyle: You can ease up on aggressive saving and let time do the work.
- Best for: Younger people who want to spend their 30s and 40s more freely while still securing their future.
Take time to figure out which version resonates with you. It will shape how much you need to save and how you structure your life.
https://wealthytraders.online/social-security-benefits/
How to Build Your FIRE Plan: A Step-by-Step Guide
Now let’s get practical. Here’s how to start your own journey to financial independence.
Step 1: Track and Cut Expenses Aggressively
FIRE starts with knowing exactly where your money goes. Use apps like Mint, YNAB, or a simple spreadsheet for 30 days.
Then, identify your biggest expense categories:
- Housing (often 30%+ of income)
- Transportation
- Food (eating out, groceries)
- Subscriptions and entertainment
- Insurance premiums
FIRE-inspired ideas to reduce expenses:
- House hack: Buy a duplex, live in one unit, rent the other.
- Downsize: Live in a smaller home or cheaper city.
- Drive used cars: Purchase reliable used vehicles in cash.
- Cook at home: Limit restaurants and meal delivery.
- Cancel unused subscriptions and negotiate bills.
Remember: every dollar saved is a dollar that can be invested.
Step 2: Maximize Your Income
You can only cut expenses so far. Increasing your income speeds up FIRE dramatically.
Consider:
- Ask for a raise or change jobs for a higher salary.
- Start a side hustle (freelancing, consulting, tutoring).
- Build passive income streams — like dividend stocks, digital products, or rental properties.
I’ve covered these in detail throughout this series:
- 15 Passive Income Ideas That Actually Work in 2024 →
- The Passive Income Blueprint →
- Building a Dividend Portfolio →
Step 3: Invest Aggressively (But Wisely)
FIRE relies on investing your savings in assets that grow over time. The most common strategy is index fund investing — buying low-cost funds that track the entire stock market.
- S&P 500 index funds: Historically return ~7-10% annually after inflation.
- Total-market funds: Diversify across thousands of companies.
- Dividend growth stocks: For a stream of cash flow in early retirement.
Use tax-advantaged accounts like a 401(k), Roth IRA, and HSA. This minimizes taxes and accelerates your wealth building.
For more on choosing accounts, read my 401(k) vs IRA guide →.
Step 4: Optimize Your Taxes
The less you pay in taxes, the faster you achieve FIRE.
- Max out retirement accounts.
- Use a Health Savings Account (HSA) — triple tax-free.
- Consider a taxable brokerage account for flexibility.
- Use capital gains harvesting strategies.
Step 5: Stay the Course
FIRE is a marathon, not a sprint. The markets will have ups and downs. Your income may fluctuate. Life will throw curveballs. But consistent investing over 10–20 years is the secret.
Investment Strategy for FIRE: What Retire Early Investors Buy
When you’re retiring in your 40s, your portfolio needs to last 50+ years, not 30. That means your asset allocation should be slightly more conservative but still growth-oriented.
Common FIRE portfolios:
| Asset Type | Typical Allocation | Purpose |
|---|---|---|
| Total stock market index funds (e.g., VTI, VTSAX) | 60–80% | Growth and long-term returns |
| International stock index funds | 10–20% | Diversification |
| Bond index funds (e.g., BND) | 10–20% | Stability and reduced volatility |
| Real estate investment trusts (REITs) | 0–10% | Alternative income source |
Why dividend stocks are popular in the FIRE community
Dividend stocks provide cash flow without selling shares. This can be especially helpful during market downturns — you collect dividends without touching your principal.
I list my top picks in Dividend Stocks for Passive Income →.
FIRE and Passive Income: The Perfect Combination
One misconception is that FIRE requires a massive salary. Actually, one of the most powerful accelerators is passive income.
When you build passive income streams:
- Your savings rate increases.
- Your required FIRE number decreases.
- You’re less dependent on a single employer for income.
- You can “retire” on your own terms even before reaching your full number.
Great passive income ideas to pair with FIRE:
- Digital products — create once, sell forever.
- Affiliate marketing — earn commissions on content you create once.
- Rental properties — monthly cash flow from real estate.
- Dividend stocks — quarterly income with zero effort.
Here are the guides:
https://wealthytraders.online/estate-planning-basics/
Common Challenges (and How to Overcome Them)
Being a FIRE seeker isn’t always easy. Here are the most common obstacles and how to handle them.
1. Low Income
You might think FIRE is only for high earners. Not true. The math works for anyone willing to save aggressively and optimize expenses.
The fix: Focus on increasing your income and keeping your expenses flat. Even on $40,000/year, a 50% savings rate is possible if you live frugally.
2. Market Volatility
A stock market crash right before retirement can be scary.
The fix: Build a “bond tent” as you approach retirement — a higher allocation to bonds to reduce risk. Keep 2–3 years of expenses in cash or short-term savings to ride out downturns.
3. Healthcare Costs
Retiring early means you’ll need healthcare before Medicare kicks in at 65.
The fix: Factor $1,000–$1,500/month into your FIRE number for insurance premiums. Look into subsidies through the Affordable Care Act (ACA) marketplace — your low income in early retirement often means cheap premiums.
4. Boredom or Lost Identity
Many people work for meaning and social connection. Retiring early can trigger identity crises.
The fix: Develop hobbies, build a social network, consider part-time volunteering, or start passion projects. FIRE doesn’t have to mean doing nothing — it means doing what you love.
5. Social Pressure and FOMO
Friends might think you’re extreme for living frugally.
The fix: Surround yourself with like-minded people (FIRE communities). Set boundaries and remember your long-term goal.
Is FIRE Realistic for Everyone?
Let’s be honest: FIRE isn’t for everyone. It requires extreme discipline, strong earning power, and a willingness to say “no” to social expectations.
However, the principles of FIRE — tracking expenses, saving aggressively, investing in index funds, and building passive income — are universally beneficial. Even if you don’t want to retire at 40, adopting some of these habits will make your retirement at 60 much more comfortable.
The goal isn’t to become a fanatic. It’s to gain control over your time and finances.
Frequently Asked Questions
What is the FIRE movement in simple terms?
FIRE is a movement where people save a large percentage of their income (often 50%+) to achieve financial independence and retire significantly earlier than the traditional retirement age.
How much money do I need for FIRE?
The standard formula is your annual expenses multiplied by 25 (the 4% rule). If you spend $50,000 a year, you need $1.25 million invested.
What is the typical FIRE age?
Most FIRE followers aim to or do retire in their 30s, 40s, or early 50s. There’s no exact age — it’s about when your portfolio can support your lifestyle.
How does the 4% rule work?
The 4% rule says you can withdraw 4% of your portfolio in your first retirement year, then adjust for inflation, and have a high probability of your money lasting 30+ years.
Can I achieve FIRE with an average salary?
Yes. It’s more about your savings rate than your salary. If you live on 40% of your income and save 60%, you can achieve FIRE in about 12 years, regardless of the actual dollar amounts.
Should I use a 401(k) or Roth IRA for FIRE?
Max out both. Many FIRE savers use a “Roth pipeline” — converting Traditional 401(k)/IRA money to Roth in early retirement to avoid penalties. This is complex, so consult a tax professional for details.
What is the biggest risk to FIRE?
The biggest risk is sequence-of-returns risk — a market crash in the early years of retirement. Mitigate it with a diversified portfolio, cash reserves, and flexible spending.
Final Thoughts
The FIRE movement isn’t about deprivation, though it looks that way from the outside. It’s about intentional living — deciding exactly what you want out of life and aligning your money with those values.
The math is simple. The execution is the hard part. But thousands of people have done it, and you can too.
Here’s your action plan to start today:
- Calculate your current expenses and savings rate.
- Set a target FIRE number (expenses × 25).
- Open or maximize tax-advantaged accounts.
- Build income streams (salary, side hustle, passive).
- Commit to the journey, and revisit your plan every quarter.
And if you’re not ready to dive into extreme frugality? That’s fine. Everything in this series — from passive income to retirement planning — is designed to give you more freedom, regardless of when you retire.
If you enjoyed this guide, keep building your financial knowledge with these resources:
- Social Security Benefits: Maximizing Your Retirement Income →
- Estate Planning Basics →
- Dividend Stocks for Passive Income →
Now, take a deep breath, open your budget, and make one small change today. The path to FIRE starts with a single step — and you just took it.